The saving you can't catch up on
You can catch up on a pension. You can't catch up on a life. Five things your job is quietly giving you, and why they can't be bought back later.

I’ve stretched my summer out to mid-September. I’m writing this on the last leg of it – somewhere between Italy and London, bike in tow, testing cross-continent train travel to its limits!
Which is giving me a good many hours to reflect back over the summer. The start feels like an age ago.
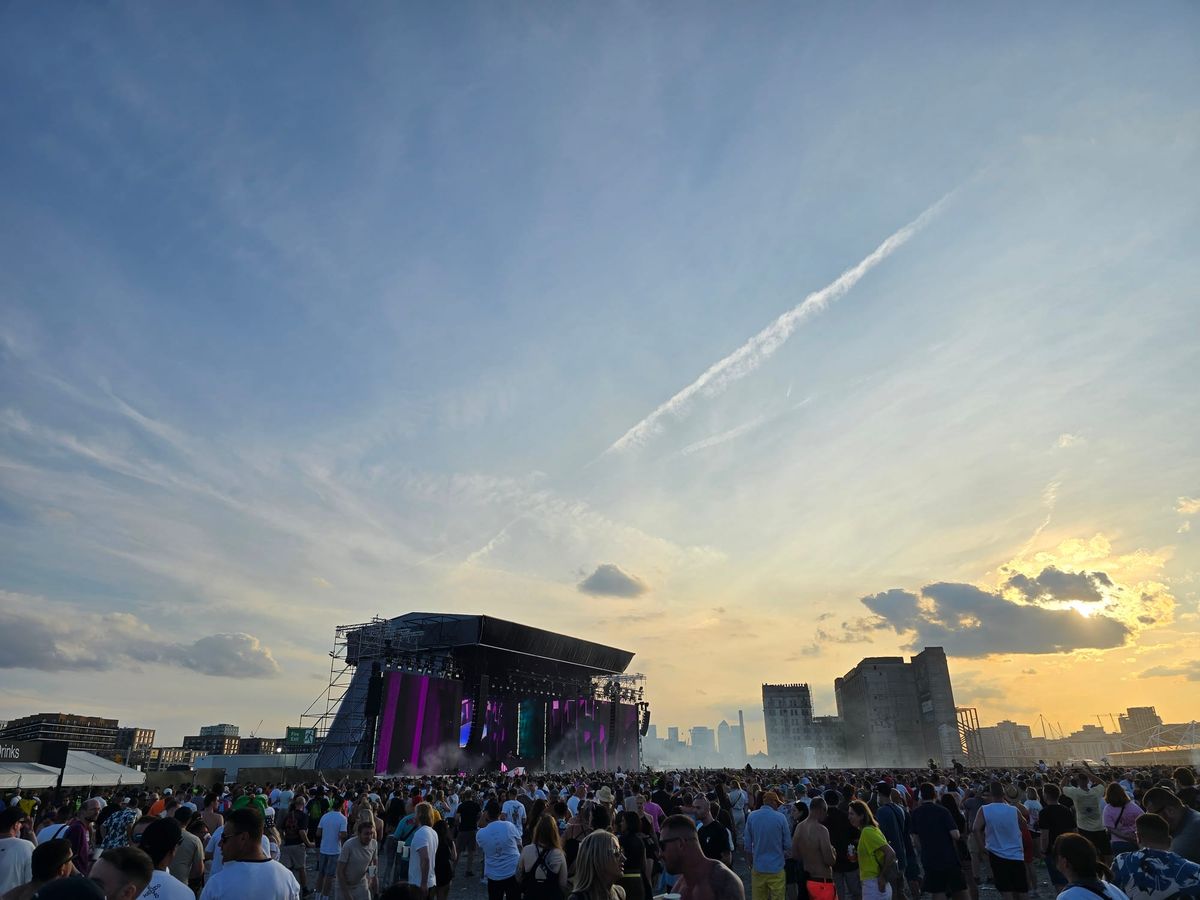
For me, it was at a venue called Silverworks Island, in east London, on one of those absurdly hot afternoons. Enjoying the build-up to the main act of the night, Above & Beyond. The site was a half-abandoned industrial yard. The searing heat gave it a “Mad Max” dystopian vibe. It was the kind of place you enjoy whilst you can, because the bulldozers are already booked.
What is planned to replace it – Silvertown – is at least trying to be and do something: net biodiversity positive, buildings reused where possible, zero-carbon heating. Let’s see whether it turns out to be a genuine new community (I hope), or just another wasted development opportunity.
But the afternoon wasn’t just about the venue, or the music. Festivals are also about the people.
We met Theresa. Recently turned sixty. A serious Above & Beyond fan who had left her daughter and husband to their own devices in London, and come on her own – and who had very nearly not come at all. Because turning up alone at sixty to a scrapyard full of strangers is, after all, a lot to ask of someone.
We got talking about the environment, and connected over our different ways of obsessing about it - hers through plastic bottles, and clearing them up. But the conversation moved to dancing, and by the end of the day she had no regrets about her decision to come. So much so that the following week she called in to the Above & Beyond podcast to give us a personal shout-out for our small part in her memorable afternoon.
This is me returning the favour. And not something that she asked for. To let her know that afternoon was memorable for me too. The dancefloor has no age limit. It's stayed with me all summer.
It's also a thought that goes well beyond the dancefloor. Most of us are brought up on a life in three neat stages: we learn, we work, and we put our feet up. Many things we'd actually like to do get deferred to the third one, when work can finally stop getting in the way. And we assume there's a right age to move between them, or at least someone tells us what that age should be.
But is there? If the dancefloor has no age limit, I don't see why what many of us call “retirement” needs one either. As my mentor says, retirement is just another life transition. And life transitions can happen at any age. So what are we all deferring? And if we defer it, will it still be there when we finally get round to it?
The second kind of saving
We're fluent in one type of saving. Saving regularly into a pension. Topping up your ISA when you can. An appreciation that investment returns are powerful, and mean that starting early is important. There's an entire industry built on teaching you this.
There's a second type of saving, noone has yet built a killer app for. The five things a working life quietly supplies: purpose, identity, relationships, structure, wellbeing. (Credit to: Robert Atchley's The Sociology of Retirement, and Dan Haylett's Humans vs. Retirement podcast.)
You're not saving for them because you're not paying for them. They come bundled with the job, like the coffee and the desk. Nobody sends you a statement.
The key isn't the relative importance of each type of saving. What's important is that one is easily recoverable, and the other isn't. If you reach sixty and the pension is too light, the fix is not pleasant but it exists. Work two more years. Spend less. Sell the house and buy a smaller one. None of that is fun, but it offers a workable solution.
If you reach sixty, and your five pillars are light, there is no equivalent easy fix. You can't work overtime on a friendship you stopped answering ten years ago. There's no lump sum that buys you a reason to get out of bed for that you genuinely believe in. There is no catch-up allowance for the person you used to be before the job took all of them.
The first you can put a number on. The second you can't.
Which turns the usual order of priority upside down. We treat the money as the urgent thing and the rest as what sorts itself out once the money is sorted. It's the other way round. You can catch up on a pension. You can't catch up on a life.
So when do you start? The honest answer is: the first time you seriously picture yourself not doing this job. For most people that lands somewhere between the mid-forties and the early sixties – which is also the cruellest possible answer, because that is the stretch of life with the least room in it. Parents who need a little more from you every year. Children who haven't finished needing you either. And a job that has finally started paying properly, which is the same job that has finally started asking for everything.
This is the decade you're told to save hardest. It's also the decade with nothing spare in it. No spare evening, no spare money, no spare version of you.
Which is why this doesn't get done in the margins. Nobody in that decade is going to rebuild five things in the gaps between emails.
And it isn't that people don't know what matters to them. Most people know precisely what matters to them, and could tell you in about ninety seconds. It's that thinking about it is the only thing on the list with no deadline attached - so it never gets a slot, and the years go by with the question still open.
So it isn't a plan in the sense of another project to maintain. It's carving out the time, once, to think properly - and coming out of it with something small enough and regular enough to survive an ordinary week.
One contribution at a time.
The five contributions
So what does saving into one of these actually look like, on a Monday, when the week is already full?
Not a programme. One modest thing per pillar. Five things you could start this month without rearranging your life.
Purpose. For the next month, at the end of each week, write down the one thing you did that you'd have done anyway if nobody had paid you. It's rarely the whole job. It's usually a surprisingly small slice of it - and you almost certainly already know which slice.
After four weeks you'll have a short and slightly surprising list, and that list is the raw material. Purpose isn't waiting to be found at sixty-five. It gets discovered in mid-life, and grown into. The advantage of starting now is that you're doing it from behind a salary, which means a false start costs you a few Saturdays rather than your confidence at the precise moment confidence is hardest to replace.
Identity. Find one room where nobody knows what you do for a living. A new class, a five-a-side team, a volunteering shift, or if you can bring yourself to it: "a networking event".
The point isn't the activity. It's that you'll have to answer "so what's your story?" without reaching for the job title – and most of us have not had to do that in a long while. It's uncomfortable the first few times. Then it's the most useful rehearsal available, because the day the title goes, that's the only version of the answer you'll have left.
Relationships. Write down the six people you'd call if something went badly wrong. Now cross out anyone you only ever see because of work. You may be surprised by what's left.
Adult friendships don't end – they thin, quietly, without anyone deciding, over about fifteen years. Work often holds far more of your social scaffolding than you'd guess. None of it survives your last day. Make sure friendships have a reason to exist that isn't the office. One standing date. Same day each month.
Structure. One commitment where somebody notices if you don't turn up. That last part is the active ingredient. Work imposes a shape on your week whether you want one or not, and a great many people discover on the day after they stop that they'd been renting their routine rather than owning it.
One standing thing is enough. The point isn't the activity, it's having something else already running when the imposed version disappears.
Well-being. Pick one health habit you'd keep if you could only keep one, and do that on the days you don't feel like it. You are, whether you think about it this way or not, training for a specific event: carrying your own shopping, getting up off the floor, walking up a hill at seventy-five. Almost nobody trains for it, because it has no date on it.
This is the pillar where the arithmetic is most forgiving and the stakes are highest: consistency beats intensity by a distance, and what you do in this decade sets the length of the good part. You are not, in mid-life, maintaining your health. You're deciding how much of the retirement you're funding you'll actually be well enough to use.
You can add to a pension at sixty. You cannot add twenty years of movement.
None of that is a life overhaul, and it isn't meant to be. It's five small standing orders. The reason to set them up now is the same reason you set up the financial one at thirty – not because this month's contribution matters, but because the next twenty years of them do.
And there's a version of this that's larger than you. Most of us assume our climate footprint is a matter of flights and diets and what we drive. All matter. But for anyone with a skill and fifteen working years left, the largest environmental decision you could ever make is what you point those years at.
The better question
A mid-life financial review asks one question: is your pension on track? It's a fair question. It's just an odd one to ask on its own, given it's the only part of this you can still fix at sixty.
I've spent twenty years in a profession that is very good at measuring things. One of the quiet costs of being good at measuring things is that you start treating everything else as optional. It isn't optional. It's most of it.
Fifteen million people in this country are on course for an inadequate retirement income. The standard answers are save more, or work longer – and working longer genuinely does help. For most people, another five years of earning moves the numbers more than any fund choice ever will.
But look at what that answer assumes. It assumes you can stand the work. Nobody extends a career they've been enduring; they leave it at the first opportunity they can afford, and often before. So the most-recommended financial fix in the country quietly depends on whether there's any purpose left in what you do – which is the one thing nobody in the room is measuring. At sixty, what you can still earn is usually worth more than what you've saved. These five decide whether you can spend it.
And when the job goes – whether you chose it or it chose you – the instinct is to replace the income. That's the visible loss, and it's the one everyone else asks about. Five things gone, and we go looking for one.
We've built an entire industry around the variable you can fix late, and left people to work out the other five that potentially matter more.
I'm not alone in thinking so. My mentor Steve Conley has been making this point too: the problem usually isn't that you don't have enough, it's that you haven't designed the next phase yet. Although sometimes it genuinely is the money, and nothing here replaces dealing with that.
The better question is whether the life is on track, with the pension as one input rather than the whole picture. What do I want the good years to look like? Which of the five am I quietly running down? What has to start now because it can't be started later?
That's a conversation rather than a calculation, and it takes longer than an hour. But it's the one that changes what you do on Monday. It is the conversation the Financial Future MOT is built to start, if you would like a hand having it.
Back to the dancefloor
You can catch up on a pension. You can't catch up on a life.
Work is just the clearest case, because the ending is scheduled. Everything else that takes the five away – the diagnosis, the redundancy, the phone call about a parent – arrives without a date on it.
So this isn't an invitation to save more. It's an invitation to notice what you've been deferring until you've got time, and to start one of them this month, while the job is still paying for the rehearsal.
Theresa, at sixty, wasn't marking the end of anything. She'd just kept hold of the life that puts you on a dancefloor at sixty.
If this resonated, here are some earlier articles on the same ground:
• The art of retiring well – the fuller treatment of the five pillars, and what they look like once you're actually there rather than preparing for it.
• When the Los Angeles fires became a catalyst – the transition I made myself, and why it was slower and rather less cinematic than the title suggests.
• What if we invented the pension again from scratch? – the systemic version of the argument: what we'd design if we started today, and why long horizons make that so hard.
Disclaimer:
Planet Positive Planning Ltd provides educational financial services. This is not a regulated activity and does not require authorisation by the Financial Conduct Authority. Nothing here is a personal recommendation, or advice on the merits of any particular investment, fund or provider, and none of it is tailored to your circumstances. An approach that suits one person may not suit another. Past performance is not a guide to future results, and investments can fall as well as rise. For a recommendation for your own situation, speak to an FCA-regulated financial adviser.